
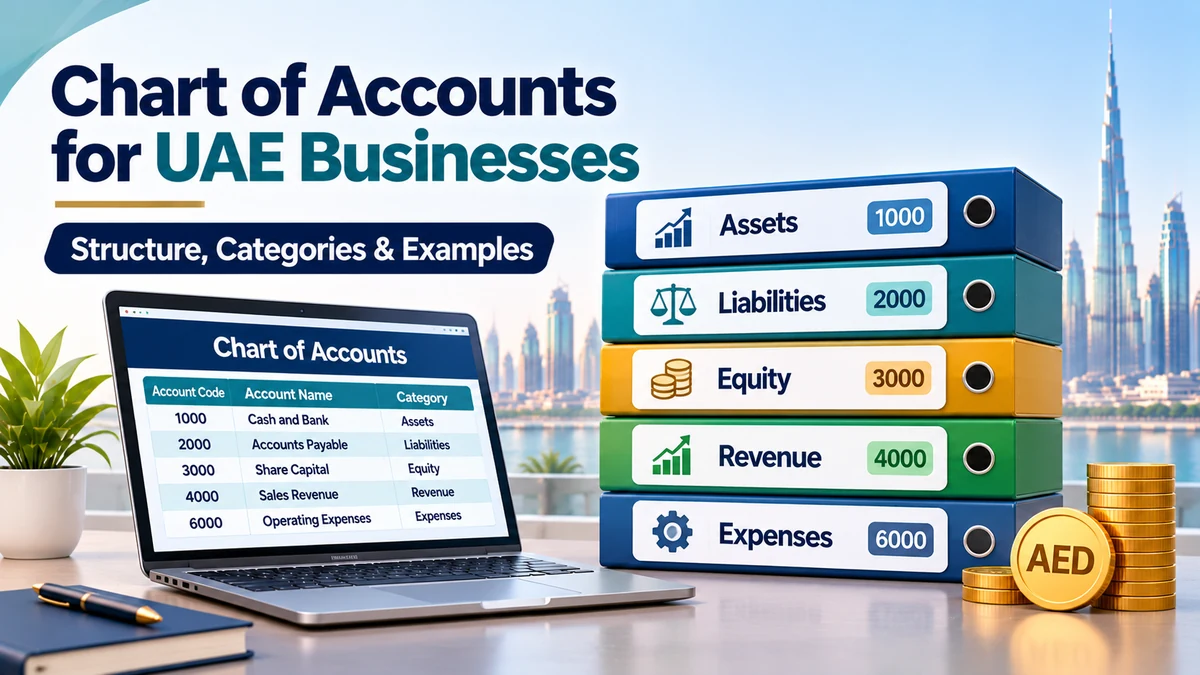
A chart of accounts UAE businesses use is the complete, organised list of every account in which a company records its financial transactions. It is the backbone of the accounting system: every sale, purchase, salary payment, VAT entry and bank transfer is posted to one of these accounts. A well-designed chart of accounts makes bookkeeping faster, financial statements clearer and VAT and corporate tax reporting far easier.
Many small businesses in Dubai, Abu Dhabi, Sharjah and the free zones start with the default list that comes with their accounting software and never adapt it. Over time, this leads to messy reports, misclassified expenses and hours wasted at year-end. This guide explains the chart of accounts structure, the five main accounting account categories, UAE-specific accounts you should include, and a practical chart of accounts example you can adapt for your business.
What Is a Chart of Accounts?
A chart of accounts (often shortened to COA) is a structured index of all the general ledger accounts a business uses. Each account usually has:
- An account code: a number that identifies the account and its category, such as 1010 or 6100.
- An account name: a clear description, such as “Cash at Bank – Emirates NBD” or “Office Rent”.
- An account type: asset, liability, equity, revenue or expense.
- A description (optional): guidance on what should be recorded in that account.
Think of the chart of accounts as the filing cabinet of your finances. Each drawer is a category, and each folder inside it is an individual account. When the cabinet is well organised, anyone can find what they need. When it is not, important information gets lost.
How Does a Chart of Accounts Help Financial Reporting?
Your financial statements are built directly from your chart of accounts. Asset, liability and equity accounts flow into the balance sheet, while revenue and expense accounts flow into the profit and loss statement. A clear accounting chart of accounts helps businesses:
- Produce accurate balance sheets and profit and loss statements.
- Prepare VAT returns more efficiently by separating standard-rated, zero-rated and exempt transactions.
- Support corporate tax calculations by identifying non-deductible or partially deductible expenses.
- Track profitability by product, service, branch or department.
- Compare performance across months and years consistently.
- Give auditors, banks and investors reports they can understand quickly.
In the UAE, businesses generally prepare financial statements in line with International Financial Reporting Standards (IFRS), and smaller businesses may be able to use IFRS for SMEs depending on their circumstances. A chart of accounts aligned with IFRS categories makes this much simpler.
What Are the Five Main Account Categories?
Every chart of accounts structure is built on five core accounting account categories:
| Category | What It Represents | Financial Statement | Typical Code Range |
|---|---|---|---|
| Assets | Resources the business owns or controls | Balance Sheet | 1000–1999 |
| Liabilities | Amounts the business owes to others | Balance Sheet | 2000–2999 |
| Equity | The owners’ interest in the business | Balance Sheet | 3000–3999 |
| Revenue | Income earned from business activities | Profit and Loss | 4000–4999 |
| Expenses | Costs incurred to run the business and earn revenue | Profit and Loss | 5000–9999 |
These categories follow the basic accounting equation: Assets = Liabilities + Equity. Revenue increases equity, while expenses reduce it.
What Are Asset and Liability Accounts?
Asset Accounts
Asset accounts are usually split into current assets (expected to be used or converted to cash within 12 months) and non-current assets (held for longer periods). Common examples include:
- Petty cash and bank accounts
- Accounts receivable (trade debtors)
- Inventory
- Prepaid expenses, such as prepaid rent and insurance
- Security deposits, such as rent deposits and utility deposits
- VAT recoverable (input VAT)
- Furniture, equipment, vehicles and leasehold improvements
- Accumulated depreciation (shown as a reduction against fixed assets)
Liability Accounts
Liability accounts are likewise split into current and non-current liabilities. Common examples include:
- Accounts payable (trade creditors)
- Accrued expenses and accrued salaries
- VAT payable (output VAT)
- Corporate tax payable
- Short-term loans, overdrafts and credit cards
- Customer advances and deposits received
- Provision for employees’ end-of-service benefits
- Long-term bank loans
Chart of Accounts Example for a UAE Small Business
Below is an illustrative chart of accounts example for a small UAE trading and services company. It is a starting framework, not a mandatory template. Your accountant should adapt it to your business activities, legal structure and reporting needs.
| Code | Account Name | Category | Example Use |
|---|---|---|---|
| 1000 – Assets | |||
| 1010 | Petty Cash | Current Asset | Small office cash expenses |
| 1020 | Bank – Current Account (AED) | Current Asset | Main operating bank account |
| 1030 | Bank – USD Account | Current Asset | Foreign currency receipts and payments |
| 1040 | Payment Gateway Clearing | Current Asset | Online sales awaiting settlement |
| 1100 | Accounts Receivable | Current Asset | Unpaid customer invoices |
| 1150 | Post-Dated Cheques Received | Current Asset | Customer PDCs not yet due |
| 1200 | Inventory | Current Asset | Stock held for sale |
| 1300 | Prepaid Rent | Current Asset | Rent paid in advance by cheque |
| 1310 | Prepaid Insurance | Current Asset | Annual medical or business insurance |
| 1350 | Security Deposits | Current/Non-current Asset | Rent and utility deposits |
| 1400 | VAT Input (Recoverable) | Current Asset | VAT paid on eligible purchases |
| 1500 | Furniture and Fixtures | Non-current Asset | Office furniture |
| 1510 | Computers and IT Equipment | Non-current Asset | Laptops, servers, printers |
| 1520 | Motor Vehicles | Non-current Asset | Company vehicles |
| 1590 | Accumulated Depreciation | Contra Asset | Total depreciation charged to date |
| 2000 – Liabilities | |||
| 2010 | Accounts Payable | Current Liability | Unpaid supplier invoices |
| 2050 | Post-Dated Cheques Issued | Current Liability | Supplier or rent PDCs not yet cleared |
| 2100 | Accrued Expenses | Current Liability | Expenses incurred but not yet invoiced |
| 2110 | Salaries Payable | Current Liability | Payroll due to staff |
| 2200 | VAT Output (Payable) | Current Liability | VAT charged on sales |
| 2210 | VAT Control / Settlement | Current Liability | Net VAT due to or from the FTA |
| 2250 | Corporate Tax Payable | Current Liability | Corporate tax due |
| 2300 | Customer Advances | Current Liability | Deposits received before delivery |
| 2400 | Credit Card Payable | Current Liability | Business credit card balances |
| 2500 | Provision for End-of-Service Benefits | Non-current Liability | Gratuity obligations to employees |
| 2600 | Long-Term Bank Loan | Non-current Liability | Term financing |
| 3000 – Equity | |||
| 3010 | Share Capital | Equity | Capital contributed by shareholders |
| 3100 | Shareholder Current Account | Equity | Owner funds introduced or withdrawn |
| 3200 | Retained Earnings | Equity | Accumulated profits from prior years |
| 4000 – Revenue | |||
| 4010 | Sales – Standard Rated (5%) | Revenue | Local taxable sales |
| 4020 | Sales – Zero Rated | Revenue | Qualifying exports |
| 4030 | Sales – Exempt | Revenue | Exempt supplies, if applicable |
| 4100 | Service Income | Revenue | Consulting or service fees |
| 4900 | Other Income | Revenue | Interest, foreign exchange gains |
| 5000 – Cost of Sales | |||
| 5010 | Cost of Goods Sold | Expense | Cost of inventory sold |
| 5020 | Freight and Customs Duty | Expense | Import and delivery costs |
| 6000 – Operating Expenses | |||
| 6010 | Salaries and Wages | Expense | Monthly payroll |
| 6020 | End-of-Service Benefits Expense | Expense | Gratuity provision for the period |
| 6030 | Visa and Labour Costs | Expense | Visas, Emirates ID, medicals |
| 6100 | Office Rent | Expense | Monthly rent expense |
| 6110 | Utilities (DEWA/ADDC/SEWA) | Expense | Electricity and water |
| 6200 | Trade Licence and Government Fees | Expense | Licence renewals and approvals |
| 6300 | Marketing and Advertising | Expense | Digital ads, printing, events |
| 6400 | Professional Fees | Expense | Accounting, audit, legal |
| 6500 | Bank Charges and Payment Fees | Expense | Bank and gateway fees |
| 6600 | Depreciation Expense | Expense | Periodic depreciation charge |
| 6700 | Entertainment Expense | Expense | Client entertainment (track separately for tax) |
| 8000 – Tax | |||
| 8010 | Corporate Tax Expense | Expense | Corporate tax charge for the year |
Why UAE Businesses Need Country-Specific Accounts
A generic template downloaded online often misses accounts that matter in the UAE accounting structure. Pay particular attention to:
- VAT accounts: separate input VAT, output VAT and a VAT control account so you can reconcile each VAT return quickly. Splitting sales into standard-rated, zero-rated and exempt accounts also reduces errors when completing the return.
- Corporate tax accounts: a corporate tax payable account and a tax expense account. It also helps to track expenses that may be fully or partially non-deductible, such as certain entertainment costs, in their own accounts.
- End-of-service benefits: a provision account so gratuity obligations are recognised over time, not only when an employee leaves.
- Post-dated cheques: PDCs are widely used in the UAE for rent and supplier payments, and tracking them separately helps cash control.
- Visa and government costs: these are significant for UAE employers and deserve their own accounts rather than being buried in “general expenses”.
- Multi-currency bank accounts: many UAE businesses trade in USD, EUR or other currencies alongside AED.
How Do You Create a Chart of Accounts?
Follow these steps to build a practical chart of accounts for small business use in the UAE:
Step 1: Understand Your Business Activities
List how your business earns money and where it spends money. A trading company needs inventory and cost of sales accounts, while a consultancy may need more detailed service income and project cost accounts.
Step 2: Choose a Numbering System
Use a consistent numbering system such as four-digit codes, with each first digit representing a category. Leave gaps between numbers (for